Keep the source with the decision
Organize original records and supporting items around the certificate or matter they explain. Retain acquisition evidence for later review.
Evidence packs
Updated · Accrella product team
A tax lien evidence pack brings the source records and supporting documents for a certificate or matter into one organized file. Accrella keeps acquisition evidence available with the matter and supports authorized document access and export records, so a reviewer can follow the basis for a decision without reconstructing the file.
Answer “why did we buy this certificate?” with the supporting record already in reach.
Organize original records and supporting items around the certificate or matter they explain. Retain acquisition evidence for later review.
Keep diligence inputs, assumptions and open questions close to the supporting documents. A complete handoff depends on the items your team has collected.
Evidence access is limited to authorized users of the relevant fund workspace. Item access records the requester and purpose and uses a time-limited link.
01
Accrella gives supporting records a place in the workflow, from acquisition review to a later handoff.
Create an evidence pack and add supporting items. The acquisition view can show retained evidence associated with the matter, giving the reviewer a clear place to start.
Keep source documents alongside the research and assumptions used in the decision. Add subsequent records as the matter develops instead of treating the initial file as final.
Provide authorized access to the relevant items and record an export against the pack. Confirm that the receiving reviewer has the documents their review requires.
02
Use this practical checklist to assemble the file. Required records depend on the matter and review; items are not all collected automatically.
Include the official publication or source reference, parcel and certificate identifiers, sale date and any receipt for the actual acquisition.
Include diligence inputs, material assumptions, open questions and the reviewed bid plan. Preserve original evidence alongside generated summaries.
Add subsequent documents and relevant correspondence so future reviewers can see what changed and what still needs attention.
03
This is an illustrative workflow. The demonstration below uses fictional inputs and does not represent a customer investment.
Match the certificate identifier to the source document and confirm that it refers to the intended parcel and sale.
Compare the diligence and proposed bid with the issues that were unresolved. Identify which missing documents or assumptions need follow-up.
Give an authorized reviewer access to the relevant items and record the handoff. Check the file’s completeness for that review.
Controlled product demonstration
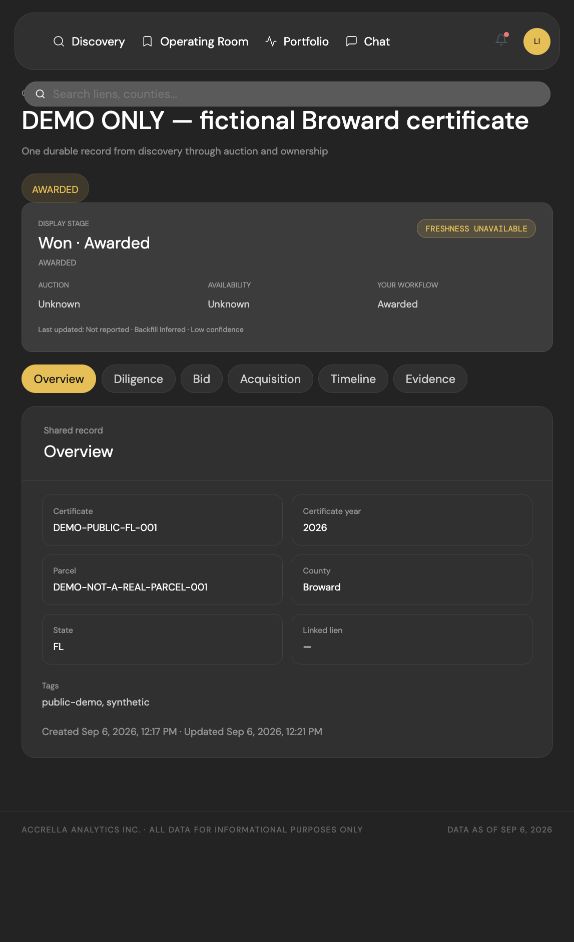
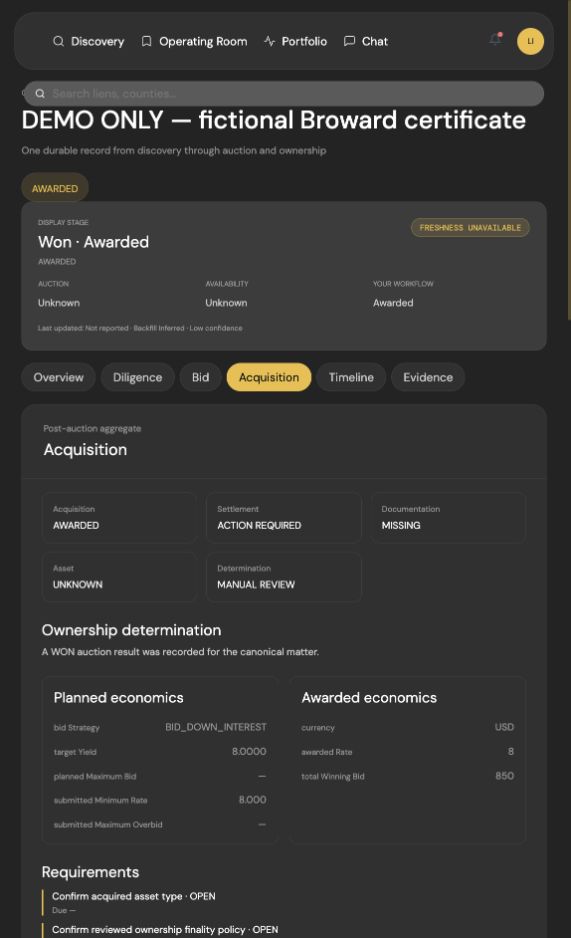
Captured September 6, 2026 in the actual Accrella application running locally at product revision 394e58c. Certificate DEMO-PUBLIC-FL-001, its parcel, amounts and dates are synthetic. This is a reproducible software demonstration, with no real taxpayer, customer outcome, auction purchase or external delivery.
This silent 36-second video presents two genuine product screenshots with explanatory captions. It is a still-image walkthrough, not a continuous recording or replay of actions.
0–9 seconds: Annotated screenshot walkthrough using two actual local product captures. DEMO-PUBLIC-FL-001 is fictional. No real parcel, taxpayer or purchase is represented.
9–18 seconds: Overview shows freshness unavailable, unknown auction status and no linked lien. Awarded records a manually entered fictional scenario, not verified ownership.
18–27 seconds: Acquisition shows Awarded, Action Required and Missing documentation. The illustrated awarded rate is 8 and total winning amount is 850 USD.
27–36 seconds: Asset type is Unknown; determination is Manual Review; requirements remain open. No certificate instrument, legal verification or external delivery is demonstrated.
Inspect dates, requests and response hashes · Inspect synthetic-data provenance and rights
No official certificate instrument, verified deadline source, attorney approval, delivery receipt or legal conclusion is supplied. The pack remains open with no recorded exports, and its evidence checklist remains incomplete. Some checklist identifiers differ from the local evidence-type registry; this sample makes no completeness claim. Inline note metadata is returned in the JSON; it is not a signed object-storage download. Instrument storage and external drafting/signature services were not configured or exercised. The import also warns that an owner name is missing for notices and attorney packets. Nothing was sent to counsel or filed.
For real source research, begin with the Broward source guide, the Palm Beach source guide, or the Florida resource guide. Fund teams can read the Florida tax certificate workflow. Explore Accrella’s software workflow and start your workspace.
FAQ
Practical answers to help you choose your next step.
It is an organized collection of source records and supporting documents associated with a certificate or matter. Accrella supports pack organization, retained acquisition evidence, authorized document access and export records.
No. The demonstration uses fictional inputs in a controlled software run. It illustrates record organization and handoff, not a customer result, completed purchase or legally sufficient file.
See the worked software exampleNo. The downloadable review packet was assembled manually from the demonstration records. The example also includes native JSON and CSV outputs; its download labels distinguish those files.
Inspect the sample downloadsNo. An evidence pack organizes supporting information. Title and legal questions still require appropriate research and professional review.
No. A pack contains the records that have been collected or added. Check required items, source dates and unresolved questions before a handoff.
Evidence operations require authorized access to the relevant fund workspace. Item access records the requester and purpose and uses a time-limited link.
Your next move
Bring research, diligence and certificate records into one workspace. Start with your next candidate or the certificates you already own.
Product information is not investment, legal or tax advice. Verify current county sources and auction requirements before acting.
First published .